What is a USDA loan?
A USDA loan is a mortgage backed by the U.S. Department of Agriculture through its Single Family Housing Guaranteed Loan Program. It was created to help moderate-income buyers purchase homes in rural and some suburban areas, and its biggest draw is simple: eligible buyers can finance 100% of the purchase price with no down payment.
You don't have to be a farmer, and the home doesn't need to be on acreage. USDA loans are made by regular approved lenders — the USDA guarantees the loan, which is what lets lenders offer zero-down financing with competitive rates. For buyers who aren't eligible for a VA loan but want to keep their cash in the bank, it's one of the few true zero-down options left.
Where USDA loans work in Hampton Roads
This is the part that surprises most buyers: the property has to sit in a USDA-eligible area. In Hampton Roads, that rules out the dense urban cores — most of Norfolk, Portsmouth and the built-up parts of Virginia Beach and northern Chesapeake won't qualify.
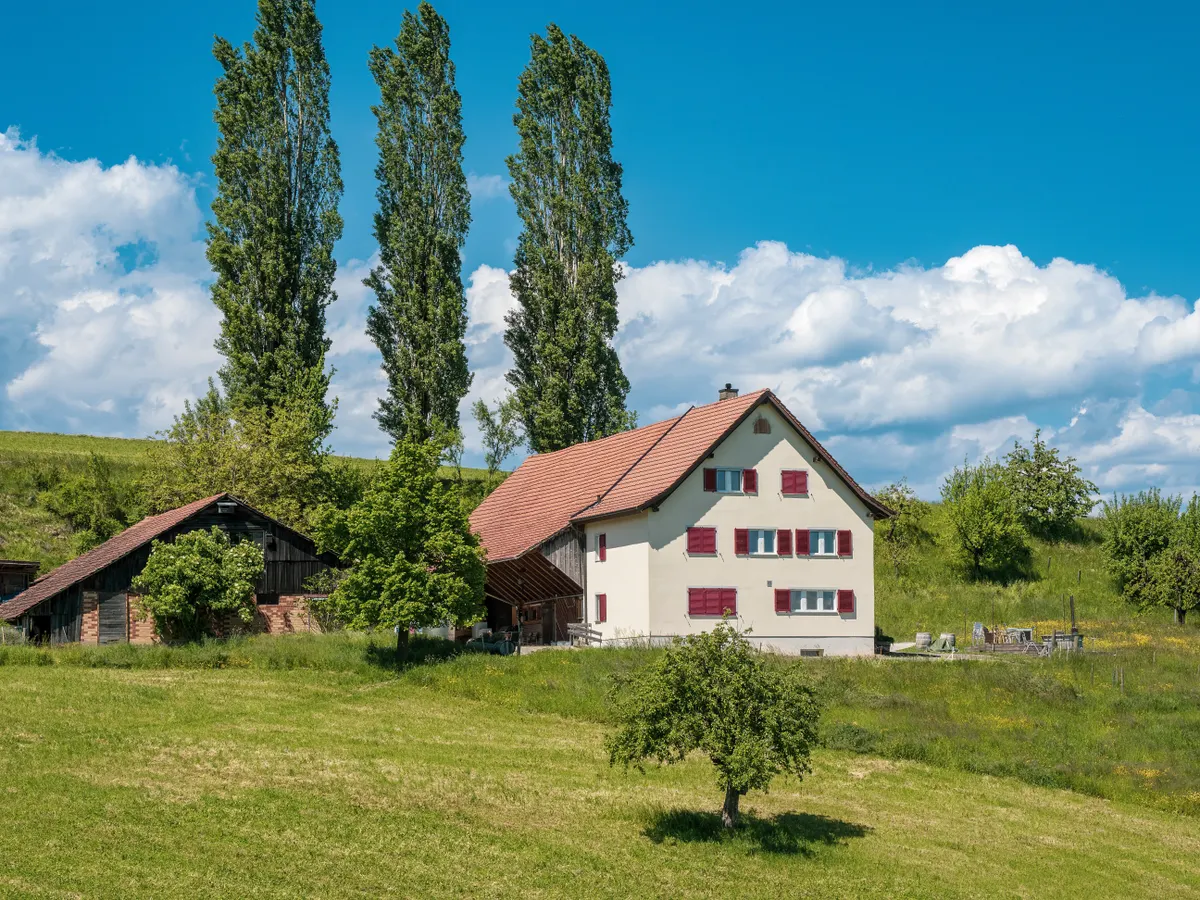
Where USDA loans do come into play is the more rural edges of the region. In Chesapeake, that mainly means parts of the southern end of the city, like Hickory and Fentress, where you'll find larger lots and more open land. Just across the city line, rural southern Virginia Beach around Pungo can also include eligible pockets. If you're drawn to that side of the region, my Hickory buying guide is a good place to start.
Eligibility is set street by street and the USDA updates its maps, so I always have buyers confirm a specific address on the USDA eligibility map before we get attached to a house. A home a half mile away from an eligible one may not qualify.
Income eligibility
USDA loans are meant for moderate-income households, so there's a cap. Your total household income generally can't exceed 115% of the median income for the area, and the limit rises with household size. That's household income, not just the borrowers on the loan — an adult child or relative living with you can count toward the total.
Because the limits vary by county or city and change each year, your lender will check your numbers against the current limits for where you're buying. Many Hampton Roads families are surprised to find they're comfortably under the cap.
Qualification basics
Beyond income and location, the requirements look a lot like any other mortgage. The home has to be your primary residence — not a rental or vacation home. Lenders will look at your credit history, steady income and your debt-to-income ratio, and many look for a credit score in the 640 range for the smoothest approval, though standards vary by lender.
USDA loans do carry fees in place of traditional mortgage insurance: an upfront guarantee fee that can usually be rolled into the loan, and a smaller annual fee built into your monthly payment. Those fees are typically lower than FHA mortgage insurance, which is part of why USDA can be the cheaper monthly option when a buyer qualifies. The home also has to pass a USDA appraisal that checks it's safe and sound.
How USDA compares to VA, FHA and conventional loans
Every loan type has a sweet spot. A VA loan is usually the best deal for eligible veterans and service members — zero down, no monthly mortgage insurance and no location restrictions. FHA loans work almost anywhere and are more forgiving on credit, but they require at least 3.5% down and carry mortgage insurance. Conventional loans reward stronger credit and let you drop mortgage insurance once you reach 20% equity.
USDA fits the buyer who isn't VA-eligible, falls under the income limit, and wants to live somewhere a little more rural. If you're torn between two areas, it's worth running the numbers both ways — use my mortgage calculator to compare a zero-down payment against putting a few percent down with FHA or conventional.
How I help USDA buyers in Hampton Roads
I connect buyers with local lenders who close USDA loans regularly and know how to keep the process on schedule. From there, I focus our search on homes that actually qualify, so you don't fall for a house that turns out to be a few streets outside the eligible area. See how I work with buyers across Hampton Roads from the first call to closing day.
Thinking a USDA loan might fit? Reach out and we'll talk through where you want to live and whether zero-down financing is realistic for you.